Almost everything we buy has moved online, and insurance is no exception.
Consumers can now research policies, calculate their needs, request quotations and complete many insurance applications digitally.
That raises an obvious question: if you want to buy insurance online in Singapore, do you actually need to speak to anyone anymore?
Sometimes, no.
But insurance products vary considerably in complexity, and the answer depends on what you are buying and how straightforward your circumstances are.
The useful way to think about it is not “online versus adviser”. It is to understand which parts of the process you can comfortably handle yourself and where getting help could lead to a better decision.
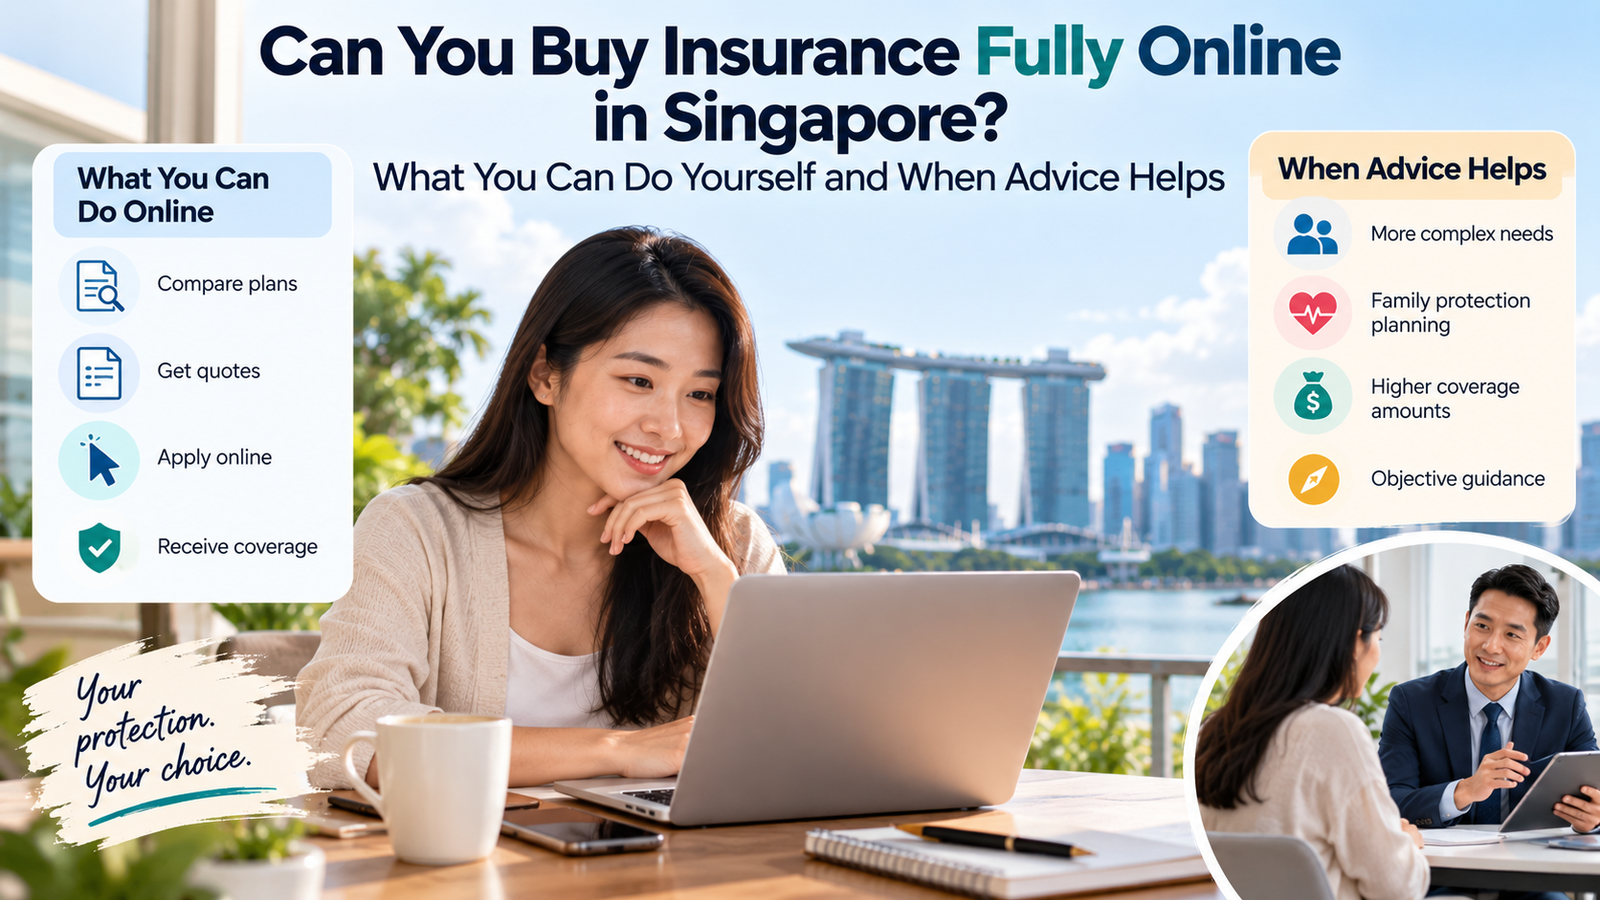
What you can easily do online
Understand the basic types of insurance
You do not need a meeting to learn the difference between life insurance, critical illness coverage, hospitalisation insurance, travel insurance or home insurance.
Good online guides can explain what each product is designed to do, common features and the major things to look out for.
This is often the best place to start because it allows you to build some knowledge before looking at individual products.
Estimate your insurance needs
Insurance calculators can help with questions such as how much life insurance your family may need or whether there is a gap in your existing protection.
A calculator should not be treated as a perfect answer, but it can give you a useful starting point.
Compare policies
Digital comparison is particularly valuable because insurance products can be difficult to evaluate from memory.
Seeing premiums and major benefits side by side makes differences easier to identify.
The important thing is to make sure you are comparing similar coverage.
A plan with a lower premium may also have lower limits or different terms.
Request quotations
For many types of insurance, getting a quotation online is straightforward.
This makes it easier to see what different insurers may charge before deciding whether you want to proceed.
When buying online is relatively straightforward
Some insurance decisions are simpler than others.
If you understand the product, have relatively straightforward needs and are comfortable reading the terms, you may be perfectly comfortable handling much of the process yourself.
For example, someone buying a simple travel policy for an upcoming holiday may primarily want to compare limits, exclusions and price.
The level of advice required can be very different from someone reviewing decades of life and health insurance coverage for an entire family.
Online tools are most useful when they give consumers control over how much assistance they want.
When advice can still be useful
When the products are difficult to compare
Insurance policies can appear similar while working differently.
A quotation may tell you the premium and a summary of benefits but not necessarily make every trade-off obvious.
This becomes especially relevant with products that contain different definitions, benefit structures or long-term premium commitments.
If you cannot clearly explain to yourself why you prefer one plan over another, getting someone to walk through the differences may help.
When you already own several policies
Buying another policy without looking at your existing insurance can lead to duplication in some areas while leaving gaps elsewhere.
Before adding more coverage, it can be useful to understand what you already have.
This is particularly relevant after major life changes such as marriage, buying a home or having children.
When health conditions are involved
Applications for some health and life insurance products require medical information.
If you have an existing or previous condition, the application may require additional questions or supporting documents.
An insurer will ultimately decide the underwriting terms, but having help through the process can make it easier to understand what information is being requested and what happens next.
When you are considering replacing an existing policy
Cancelling an old policy and buying a new one deserves additional care.
The new policy may have different terms, premiums or exclusions, and there may be consequences from giving up an existing policy.
This is an area where making a decision purely from a new online quotation may not give you the whole picture.
What about after you buy?
Online insurance discussions tend to focus on getting to the purchase.
But insurance can last for years or even decades.
Consider what happens afterwards.
If your circumstances change, can you review your coverage?
Who handles policy servicing?
What happens during renewal?
Most importantly, what happens when you have a claim?
Some consumers prefer dealing directly with insurers. Others value having someone who can help them understand the claims process and the documents required.
Neither approach is inherently right or wrong.
But it is worth knowing what support comes with the route you choose before purchasing the policy.
A better model may be online plus human support
Technology has made the research and comparison stages of insurance much easier.
It gives consumers an opportunity to learn independently rather than entering a conversation without any idea of what is available.
Human advice can then be used where it actually adds value.
That may be explaining a difficult choice, reviewing an existing portfolio or helping with an application that is not straightforward.
Platforms such as Planner Bee allow consumers to research and compare insurance online across 29 insurers and more than 500 products, while licensed representatives are available when advice or application support is needed.
Support also continues through policy servicing, renewals and claims.
That combination reflects how many people actually prefer to make financial decisions today: do some research yourself first, then ask for help where you need it.
Buying online should mean having more information, not less
The biggest advantage of digital insurance is not simply speed.
It is access to information.
Consumers can research products, compare different insurers and think about their needs before making a commitment.
Use that advantage.
If a policy is straightforward and you understand it, completing the process online may be all you need.
If you are unsure what you are comparing, have complicated circumstances or simply want a second opinion, ask someone to help.
The goal is not to complete the purchase with as little human interaction as possible.
It is to make a good insurance decision with as much or as little assistance as you need.